Wednesday, 26 December 2018

Global Atherectomy Devices Market by Device Type, Application, End User 2022

The growth witnessed by atherectomy devices market is mainly driven by the growing target patient population, continuous product development & commercialization, favorable medical reimbursements, rising demand for minimally invasive atherectomy procedures, and strengthening distribution channels of major product manufacturers.
The global atherectomy devices market is projected to reach USD 1.45 Billion by 2022 from USD 1.08 Billion in 2017, at a CAGR of 6.1%. 
This report broadly segments the atherectomy devices market into product, application, end user, and region. 
On the basis of product, the market is categorized into directional, photo-ablative (laser), orbital, rotational atherectomy systems, and support devices. In 2017, the directional atherectomy devices segment is expected to account for the largest share of the market. It is also expected to register the highest CAGR during the forecast period. This can be attributed to the significant availability of credible clinical data to validate their clinical efficacy, rising availability of reimbursements for vascular treatment procedures across developed countries, high preference for minimally invasive procedures among medical professionals, clinical benefits offered, and ongoing technology advancements in the field of directional atherectomy.
Based on application, the atherectomy devices market is categorized into peripheral vascular, cardiovascular, and neurovascular applications. The peripheral vascular applications segment accounted for the largest share of the market and is expected to be the fastest growing segment during the forecast period. The large share of this segment is attributed to the significant availability of clinical evidence to support therapeutic efficacy of atherectomy in PVD treatment and rising availability of medical reimbursements for peripheral atherectomy procedures across developed countries.
Based on end user, the atherectomy devices market is segmented into three categories, namely, hospitals and surgical centers, ambulatory care centers, and research laboratories & academic institutes. The hospitals and surgical centers segment accounted for the largest share of the market due to the increasing adoption of atherectomy for cardiac & peripheral vascular disease treatment and growing availability of healthcare reimbursements across major countries.
This report covers the atherectomy devices market across four major geographies, namely, North America, Europe, Asia Pacific, and the Rest of the World (RoW). Of the four geographic regions studied in the report, North America is expected to command the largest share of the market in 2017. Factors such as increasing availability of reimbursements for atherectomy systems, growing adoption of atherectomy systems among medical professionals, large patient population of peripheral & coronary artery diseases, and growing number of clinical trials (that aim to evaluate the therapeutic efficacy of atherectomy systems in specific disease treatment) are driving the growth of the North American atherectomy devices market.
                               

Monday, 24 December 2018

Professional Dental Care Market Share, Size and Industry Growth ..

Geographically, the global professional dental care market is segmented into North America, Europe, Asia-Pacific, and the Rest of the World. In 2015, Europe commanded a major share of the market. 
However, Asia-Pacific is expected to witness the highest growth rate during the forecast period. Growth in the Asia-Pacific market can be attributed to rising geriatric population, increasing awareness about dental health, and medical tourism will drive the growth of this market in the APAC.

Some of the prominent players in the professional dental care market include Colgate-Palmolive Company (U.S.), The Procter & Gamble Company (U.S.), Unilever plc (U.K.), Johnson & Johnson (U.S.), Young Innovation, Inc. (U.S.), Ultradent Products, Inc. (U.S.), GC Corporation (Japan), GlaxoSmithKline plc (U.K.), Dr. Fresh, LLC (U.S.), 3M Company (U.S.), Koninklijke Philips N.V. (Netherlands), and Sunstar (Japan).

Target Audience:

  • Manufacturers of professional dental care products
  • Distributors of dental care products
  • Dental R&D institutes
  • Dental laboratories
  • Government associations and dental practitioners
  • Market research and consulting firms
  • Venture capitalists and investors
The global professional dental care market is estimated to grow at a CAGR of 4.5% from 2016 to 2021 to reach USD 961.0 Million by 2021.

Factors such as growing number of small/ private dental clinics, rising incidences of dental caries, increasing disposable incomes in emerging countries, growing awareness about dental hygiene, and economic gains for dental practitioners are the major factors driving the growth of the global market. However, increasing number of large/group dental practices and reluctance to adopt dental dispensing practices by dental practitioners are expected to restrain the growth of this market to certain extent.

To Know More

Thursday, 20 December 2018

"Global Surgical Lasers Market" - Global Industry Analysis and Forecast 2022


According to a new market research report "Surgical Lasers Market by Product Type (Carbon Dioxide, Argon, Nd:YAG & Diode Lasers), Procedure (Open, Laparoscopic & Percutaneous), & Application (Ophthalmology, Urology, Gynaecology, Dermatology, Dental, Cardiology, & Oncology) - Global forecast to 2021", published by MarketsandMarkets


Surgical Lasers Market is expected to reach USD 2.37 Billion by 2021; growing at a CAGR of 5.1% from 2016 to 2021.

A combination of bottom-up and top-down approaches was used to calculate the sizes and growth rates of the market and its subsegments. All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources. In this research study, all possible parameters that affect this market have been accounted for, viewed in extensive detail, verified through primary research, and analyzed to get the final quantitative & qualitative data. 
Primary interviews with key opinion leaders were also used to determine the percentage shares of each product in emerging nations. The report provides qualitative insights about growth rates and market drivers for all subsegments. It maps market sizes and growth rates for each subsegment and identifies segments poised for rapid growth in each geographic region.
Lumenis (Israel), Cynosure, Inc. (U.S.), Alma Lasers (Israel), Abbott Laboratories, Inc., (U.S.), Boston Scientific Corporation (U.S.), IPG Photonics Corporation (U.S.), Spectranetics Corporation (U.S.), Biolitec AG (Austria), Fotona d.o.o. (Slovenia), and BISON MEDICAL Co., Ltd. (South Korea) are some of the key players in the surgical lasers market.
Target Audience:
  • Surgical laser product manufacturing companies
  • Product suppliers and distributors
  • Healthcare service providers [including hospitals, specialty clinics, and ambulatory surgery centers (ASCs)]
  • Research laboratories and academic institutes
  • Clinical research organizations (CROs)
  • Government regulatory authorities
  • Independent authorities and non-government organizations
  • Market research and consulting firms
  • Venture capitalists


Wednesday, 19 December 2018

Key Revenue Pockets of Dental Sterilization Market in Upcoming Years


The global dental sterilization market is projected to reach USD 1.48 billion by 2023 from USD 1.08 billion in 2018, at a CAGR of 6.6%. 


Factors such as the increasing number of dental facilities and the growing pool of dental care personnel, growing prevalence of dental ailments, and the increasing demand for cosmetic dentistry are expected to drive the market. The emerging markets are expected to provide a wide range of growth opportunities for players in the market.


In this report, the dental sterilization market is segmented based on product, end user, and region. 

On the basis of product, the market is further classified into instruments and consumables & accessories. The sterilization packaging accessories segment accounted for the largest share of the global dental sterilization consumables & accessories market in 2017.

The large share of this segment can primarily be attributed to the short life cycle of these products, which results in their repeated and frequent purchase, as opposed to instruments which are considered as a one-time investment. On the other hand, the sterilization equipment segment accounted for the largest share of the dental sterilization instruments market. This is due to the higher cost and higher adoption rate of these equipment.

On the basis of type, the sterilization equipment market is segmented into high-temperature sterilizers and low-temperature sterilizers. In 2017, the high-temperature sterilizers segment accounted for the largest share, primarily due to the high adoption rate, ease of use, and efficiency in the sterilization of complicated as well as delicate dental devices.

Among end users, the clinics segment is the fastest growing segment of the dental sterilization market. The market for this segment is mainly driven by the demand for affordable dental care and the growing number of private practices and smaller dental units in emerging countries.

Geographically, the dental sterilization market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific is projected to grow at the highest CAGR, owing to the growing number of dental clinics and hospitals and increasing number of dental surgical procedures. Additionally, the growth of dental tourism and the dental industry is propelling the need for effective infection control in a number of APAC countries such as India, Malaysia, and Thailand.


Tuesday, 18 December 2018

Surgical Staplers Market : Industry Size, Scope and Growth Analysis 2022

A number of factors such as increasing number of surgical procedures across the globe, growing preference for minimally invasive surgeries, technological advancements, and increasing preference for surgical staplers over sutures are expected to drive the growth of the market. On the other hand, high cost of devices and availability of alternative wound care techniques may hinder the growth of the market in the coming years.
The global surgical staplers market is expected to reach USD 4.78 Billion by 2022 from USD 3.38 Billion in 2017, at a CAGR of 7.2 %.


Scope of the Report
This report categorizes the global market into following segments and subsegments:

Global Surgical Staplers Market, By Product
  • Manual Surgical Staplers
  • Powered Surgical Staplers

Global Surgical Staplers Market, By Type
  • Disposable Surgical Staplers
  • Reusable Surgical Staplers

Global Surgical Staplers Market, By Application
  • Abdominal & Pelvic Surgery
  • General Surgery
  • Cardiac and Thoracic Surgery
  • Orthopedic Surgery
  • Other Surgical Application

Global Surgical Staplers Market, By End User
  • Hospitals
  • Ambulatory Surgical Centers (ASCs) and Clinics

Global Surgical Staplers Market, By Region
  • North America
  • Europe
  • Asia-Pacific
  • Rest of the World (RoW)

Key Players
The surgical staplers market is duopolistic in nature, with two major players Ethicon Inc. (U.S.) and Medtronic plc (Ireland). Apart from these other prominent players of the market includes CONMED Corporation (U.S.), Smith & Nephew (U.K.), Purple Surgical Inc. (U.K.), Intuitive Surgical Inc. (U.S.), Welfare Medical Ltd. (U.K.), Reach surgical Inc. (China), Meril Life Science Pvt. Ltd. (India), Grena Ltd. (U.K.), B. Braun Melsungen AG (Germany), Dextera Surgical Inc. (U.S.), Frankenman International (China), and Becton, Dickinson and Company (U.S.).

Friday, 14 December 2018

Airway Management Devices Market: Objectives of the Study and Research Methodology- Global Forecast to 2023

The global airway management devices market was valued at USD 1.52 billion in 2017 and is projected to reach USD 2.10 billion by 2023, at a CAGR of 5.6% during the forecast period. 


Base year considered for the report is 2017 and the forecast period considered for this report is 2018–2023.
The growth of airway management devices market is majorly driven by factors such as rising prevalence of chronic respiratory diseases, increasing demand for emergency care, and high incidence of preterm babies are driving the growth of this market.
Request for Customization @ 

Objectives of the Study
  • To define, measure, and describe the global market by type, end user, patient age, and region
  • To provide detailed information about the major factors influencing market growth (drivers, restraints, challenges, and opportunities)
  • To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall market
  • To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
  • To forecast the size of market segments in North America, Europe, Asia Pacific, and RoW
  • To strategically analyze the market structure and profile key players in the global market and comprehensively analyze their core competencies
  • To track and analyze company developments such as partnerships, agreements, and collaborations; expansions; acquisitions; product approvals; and product launches in the market

Research Methodology

Top-down and bottom-up approaches were used to validate the size of the global airway management devices market and estimate the size of other dependent submarkets. 

Various secondary sources such as, World Health Organization (WHO), World Economic Forum, World Bank, World Federation of Societies of Anaesthesiologists (WFSA), Difficult Airway Society, British Medical Association (BMA), American Lung Association, American Society of Anesthesiologists (ASA), Centers for Disease Control and Prevention (CDC), Health Canada, Paramedic Association of Canada, Eurostat, European Society of Anaesthesiology (ESA), Dubai Health Authority (DHA), press releases, directories, industry journals, databases, and annual reports of the companies have been used to identify and collect information useful for the study of this market. 

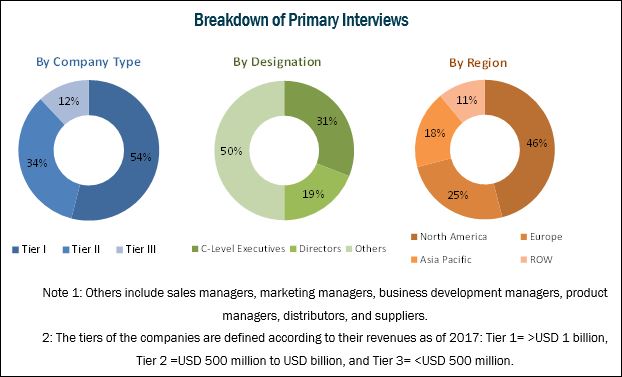
Primary sources such as experts from both supply and demand sides have been interviewed to obtain and validate information as well as to assess dynamics of this market. The breakdown of profiles of primaries is shown in the figure below:
Airway Management Devices Market

The major players in this market include Medtronic (Ireland), Smiths Medical (US), Teleflex (US), Ambu (US), KARL STORZ (Germany), Flexicare (US), Verathon (US), Olympus (Japan), Intersurgical (UK), SunMed (US), Vyaire Medical (US), and VBM Medizintechnik (Germany).

Thursday, 13 December 2018

Cardiovascular Ultrasound System Market :Industry Analysis, Market Segmentation, Size And Global Forecast to 2021

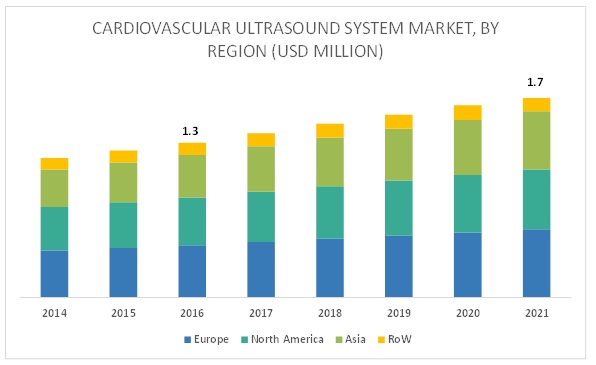
The global cardiovascular ultrasound system market is projected to reach USD 1.66 Billion by 2021 from USD 1.27 Billion in 2016, at a CAGR of 5.4% from 2016 to 2021.
In this report, the global market is segmented on the basis of test type, technology, device display, end user, and region.
Market Segmentation
Cardiovascular Ultrasound System Market, by Test Type
  • Transthoracic Echocardiogram
  • Transesophageal Echocardiogram
  • Stress Echocardiogram
  • Other Echocardiograms (Fetal and Intracardiac Echocardiograms)
Cardiovascular Ultrasound System Market, by Technology
  • 2D
  • 3D & 4D
  • Doppler Imaging
Cardiovascular Ultrasound System Market, by Device Display
  • Color Display
  • Black & White (B/W) Display
Cardiovascular Ultrasound System Market, by End User
  • Hospitals/Cardiology Centers
  • Ambulatory/Home Care
  • Other End Users (Research Institutes, Medical Device and Pharmaceutical Companies)
Target Audience:
  • Cardiovascular ultrasound system manufacturers
  • Cardiovascular ultrasound system distributors and wholesalers
  • Pharmaceutical companies
  • Various research and consulting firms
  • Research institutes
  • Contract manufacturing organizations (CMOs)
  • Original equipment manufacturers (OEMs)


Europe is expected to account for the largest market share during the forecast period.

The cardiovascular ultrasound system market is divided into four major regions-North America, Europe, Asia Pacific, and the Rest of the World (RoW). In 2016, Europe is expected to account for the largest share of this market, followed by North America. Factors such as growing product commercialization, expansion in clinical applications of HIFU coupled with their early commercialization in Europe, and growing emphasis on non-invasive procedures by patients and physicians are driving the growth of this market

Patient Portal Market Size, Market Growth Projection to 2023

The growth of the overall patient portals market can be contributed to the federal mandates like meaning use, growing patient centric appro...