Friday, 14 December 2018

Airway Management Devices Market: Objectives of the Study and Research Methodology- Global Forecast to 2023

The global airway management devices market was valued at USD 1.52 billion in 2017 and is projected to reach USD 2.10 billion by 2023, at a CAGR of 5.6% during the forecast period. 


Base year considered for the report is 2017 and the forecast period considered for this report is 2018–2023.
The growth of airway management devices market is majorly driven by factors such as rising prevalence of chronic respiratory diseases, increasing demand for emergency care, and high incidence of preterm babies are driving the growth of this market.
Request for Customization @ 

Objectives of the Study
  • To define, measure, and describe the global market by type, end user, patient age, and region
  • To provide detailed information about the major factors influencing market growth (drivers, restraints, challenges, and opportunities)
  • To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall market
  • To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
  • To forecast the size of market segments in North America, Europe, Asia Pacific, and RoW
  • To strategically analyze the market structure and profile key players in the global market and comprehensively analyze their core competencies
  • To track and analyze company developments such as partnerships, agreements, and collaborations; expansions; acquisitions; product approvals; and product launches in the market

Research Methodology

Top-down and bottom-up approaches were used to validate the size of the global airway management devices market and estimate the size of other dependent submarkets. 

Various secondary sources such as, World Health Organization (WHO), World Economic Forum, World Bank, World Federation of Societies of Anaesthesiologists (WFSA), Difficult Airway Society, British Medical Association (BMA), American Lung Association, American Society of Anesthesiologists (ASA), Centers for Disease Control and Prevention (CDC), Health Canada, Paramedic Association of Canada, Eurostat, European Society of Anaesthesiology (ESA), Dubai Health Authority (DHA), press releases, directories, industry journals, databases, and annual reports of the companies have been used to identify and collect information useful for the study of this market. 

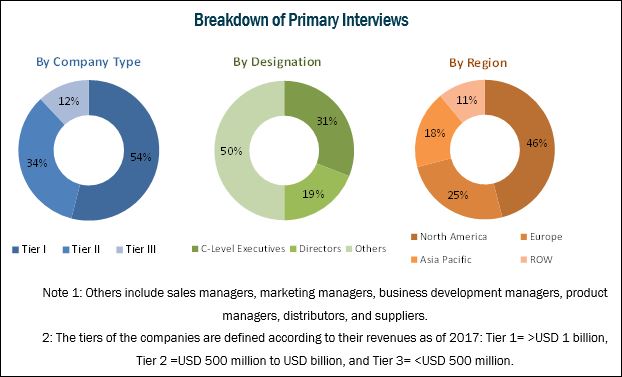
Primary sources such as experts from both supply and demand sides have been interviewed to obtain and validate information as well as to assess dynamics of this market. The breakdown of profiles of primaries is shown in the figure below:
Airway Management Devices Market

The major players in this market include Medtronic (Ireland), Smiths Medical (US), Teleflex (US), Ambu (US), KARL STORZ (Germany), Flexicare (US), Verathon (US), Olympus (Japan), Intersurgical (UK), SunMed (US), Vyaire Medical (US), and VBM Medizintechnik (Germany).

Thursday, 13 December 2018

Cardiovascular Ultrasound System Market :Industry Analysis, Market Segmentation, Size And Global Forecast to 2021

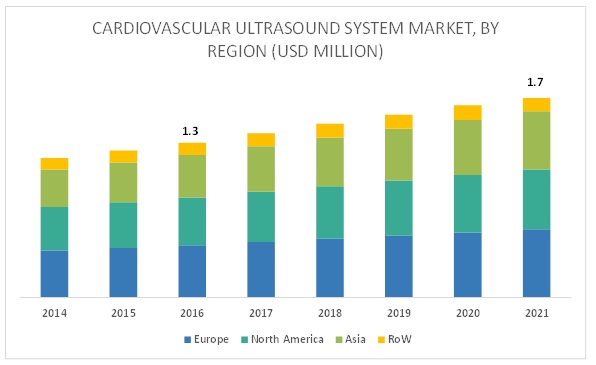
The global cardiovascular ultrasound system market is projected to reach USD 1.66 Billion by 2021 from USD 1.27 Billion in 2016, at a CAGR of 5.4% from 2016 to 2021.
In this report, the global market is segmented on the basis of test type, technology, device display, end user, and region.
Market Segmentation
Cardiovascular Ultrasound System Market, by Test Type
  • Transthoracic Echocardiogram
  • Transesophageal Echocardiogram
  • Stress Echocardiogram
  • Other Echocardiograms (Fetal and Intracardiac Echocardiograms)
Cardiovascular Ultrasound System Market, by Technology
  • 2D
  • 3D & 4D
  • Doppler Imaging
Cardiovascular Ultrasound System Market, by Device Display
  • Color Display
  • Black & White (B/W) Display
Cardiovascular Ultrasound System Market, by End User
  • Hospitals/Cardiology Centers
  • Ambulatory/Home Care
  • Other End Users (Research Institutes, Medical Device and Pharmaceutical Companies)
Target Audience:
  • Cardiovascular ultrasound system manufacturers
  • Cardiovascular ultrasound system distributors and wholesalers
  • Pharmaceutical companies
  • Various research and consulting firms
  • Research institutes
  • Contract manufacturing organizations (CMOs)
  • Original equipment manufacturers (OEMs)


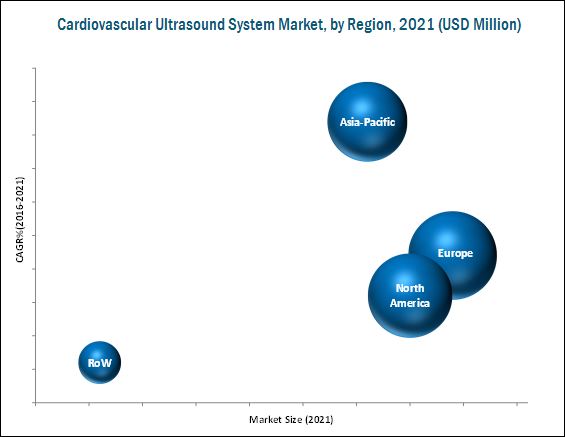
Europe is expected to account for the largest market share during the forecast period.

The cardiovascular ultrasound system market is divided into four major regions-North America, Europe, Asia Pacific, and the Rest of the World (RoW). In 2016, Europe is expected to account for the largest share of this market, followed by North America. Factors such as growing product commercialization, expansion in clinical applications of HIFU coupled with their early commercialization in Europe, and growing emphasis on non-invasive procedures by patients and physicians are driving the growth of this market

Tuesday, 11 December 2018

Gel Documentation Systems Market: Industry Insights and Global Forecast to 2023


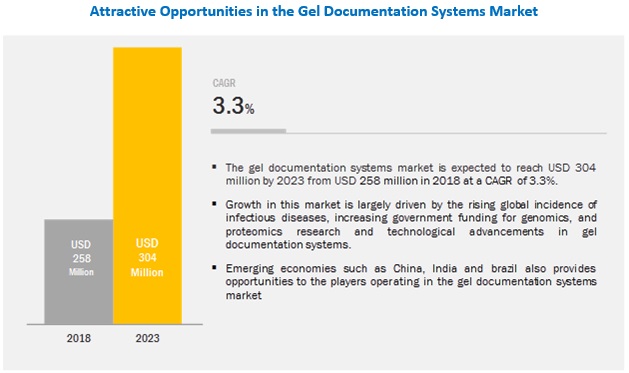
Gel Documentation Systems Market is projected to grow from USD 258 million in 2018 to USD 304 million by 2023, at a CAGR of 3.3% during the forecast period.


The major factors driving the Gel Documentation Systems Market are growing global incidence of infectious diseases and genetic disorders and increase in funding for research & development in genomics, proteomics, and electrophoresis techniques.


Report Objectives

  1.  To define, describe, and forecast the global gel documentation systems market on the basis of product, light source, detection technique, application, end user, and region
  2. To provide detailed information regarding major factors influencing growth of the market (drivers, restraints, and opportunities)
  3.  To strategically analyze the micromarkets1 with respect to individual growth trends, future prospects, and contributions to the total market
  4. To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
  5. To forecast the revenue of the market segments with respect to four main regions, namely, North America, Europe, Asia Pacific, and the Rest of the World
  6. To strategically profile the key players and comprehensively analyze their market shares and core competencies2
  7. To track and analyze competitive developments such as new product launches; agreements, partnerships, and joint ventures; mergers and acquisitions; and research & development activities in the gel documentation systems market

Based on region, the gel documentation systems market is segmented into North America, Europe, Asia Pacific, and the Rest of the World (RoW). In 2018, North America is estimated to account for the largest share due to the increasing research in the fields of proteomics and genomics, increasing R&D activities by pharmaceutical and biotechnology companies, the presence of a highly developed biotechnology research infrastructure, and the availability of government grants to support research activities.
The major players in the gel documentation systems market are GE Healthcare (US), Bio-Rad Laboratories, inc. (US), Thermo Fisher Scientific (US), LI-COR Biosciences (US), Endress+Hauser Management AG (Switzerland), Vilber Lourmat (France), Scientific Digital Imaging plc (UK), Bio-Techne (US), Cleaver Scientific (US), and Azure Biosystems (US).


Sunday, 9 December 2018

Atherectomy Devices Market by Product , Application , End User - Global Forecasts To 2022


The global atherectomy devices market is projected to reach USD 1.45 Billion by 2022 from USD 1.08 Billion in 2017, at a CAGR of 6.1%.
The growth witnessed by atherectomy devices is mainly driven by the growing target patient population, continuous product development & commercialization, favorable medical reimbursements, rising demand for minimally invasive atherectomy procedures, and strengthening distribution channels of major product manufacturers.

Scope of the Report
This report categorizes the global atherectomy devices market into the following segments and sub segments:
Global Atherectomy Devices Market, by Product
  • Directional Atherectomy Devices
  • Orbital Atherectomy Devices
  • Photo-Ablative Atherectomy Devices
  • Rotational Atherectomy Devices
  • Support Devices
Global Atherectomy Devices Market, by Application
  • Peripheral Vascular
  • Cardiovascular
  • Neurovascular
Global Atherectomy Devices Market, by End User
  • Hospitals & Surgical Centers
  • Ambulatory Care Centers
  • Research Laboratories & Academic Institutes
Factors such as stringent regulatory framework, significant adoption of alternative therapies, and dearth of well-trained surgeons to conduct atherectomy procedures are expected to restrain the growth of the atherectomy devices market during the forecast period.
The major players in the atherectomy devices market are Medtronic (Ireland), Philips (Netherlands), Boston Scientific (US), Cardiovascular Systems (US), Straub Medical (Switzerland), BIOTRONIK (Netherlands), C.R. Bard (US), and Avinger (US).

Wednesday, 5 December 2018

Point of Care Molecular Diagnostics Market : Industry Growth and Opportunities-Global Forecast to 2023

Growth in the point-of-care (POC) molecular diagnostics market is mainly driven by factors such as the increasing worldwide prevalence of infectious diseases, rising focus on decentralized diagnostics, and the growing demand for CLIA-waived molecular POC tests.
Point of Care Molecular Diagnostics Market by Product & Service (Assays, Kits, Analyzers, Software), Application (Respiratory Disease, Hospital Acquired Infection), Technology (RT-PCR, INAAT), End User (Physician Office, ICUS) - Global Forecast to 2023", published by MarketsandMarkets™


Global market is expected to reach 
USD 1440.2 Million by 2023 from USD 725.5 Million in 2018, at a CAGR of 14.7%.


By product, the assays & kits segment is expected to dominate the market in 2018 
On the basis of product & service, the market is broadly segmented into assays & kits, instruments/analyzers, software & services. The assays & kits segment is expected to hold the largest share of the market in 2018 and is also projected to grow at highest CAGR in the global POC Molecular Diagnostics Market during the forecast period. An increasing number of assays and kits in this market have been granted the CLIA-waived status, which defines that the product can be used for decentralized settings or nontraditional laboratories, including physicians' offices, emergency rooms, and health department clinics. As a result, their applications have increased, making them the largest segment.
RT-PCR technology segment is expected to account for largest share of the market in 2018 
On the basis of technology, the market is broadly segmented into RT-PCR, INAAT, and other technologies. The RT-PCR segment is expected to account for the largest share of the global POC Molecular Diagnostics Market in 2018. RT-PCR is a highly cost-effective and preferred technology for POC settings that allows for the concurrent monitoring of expression levels of multiple genetic messages. Such benefits are driving the growth of the RT PCR segment.
Based on application, the respiratory segment is expected to account for largest share of the market in 2018 
On the basis application, the market is broadly segmented into respiratory diseases, hospital-acquired infections (HAIs), sexually transmitted diseases (STDs), oncology, hepatitis, and other applications (meningococcal meningitis, malaria, herpes simplex virus, Ebola, Zika virus). The respiratory application segment is expected to account for the largest share of the global POC Molecular Diagnostics Market in 2018. Growth in this market can be attributed to the rising prevalence of influenza and TB and the rising demand for the early diagnosis and detection of these diseases, especially in emerging countries.
Based on end user, the physician offices segment is expected to account for largest share of the market in 2018 
On the basis of end users, the market is broadly segmented into physician offices, hospital EDs and ICUs, research institutes, and other end users. The physician offices segment is expected to hold the largest share of the market. This share can be attributed to the increased preference for CLIA-waived tests for influenza diagnostics and faster turnaround time of POC molecular assay tests.
North America is expected to dominate the POC Molecular Diagnostics Market in 2018 
In 2018, North America is expected to account for the largest share of the global POC Molecular Diagnostics Market. The growing prevalence of infectious diseases, increasing number of CLIA product approvals, and rising government initiatives to support the adoption of POC molecular diagnostics in this region are driving the market growth.
Some of the key players in the global POC Molecular Diagnostics Market are Roche Diagnostics (Switzerland), Abbott Laboratories (US), Biomerieux SA (France), and Danaher (US). Product development was the major strategy adopted by these major players to maintain their leadership position in the global POC Molecular Diagnostics Market.
Know more about the Point of Care Molecular Diagnostics Market: 

Tuesday, 4 December 2018

Future of Veterinary Surgical Instruments Market - Forecast to 2021

"Veterinary Surgical Instruments Market by Product (Sutures, Foreceps, Scissors, Electrosurgery Instruments, Cannulas), Animal (Canines, Felines, Large Animals) & Applications (Soft tissue, Sterilization, Gynecology, & Orthopedic Surgery) - Forecast to 2021"published by MarketsandMarkets,

Analyzes and studies the major market drivers, restraints, and opportunities in North AmericaEuropeAsia-Pacific, and Rest of the World.

Browse 175 market data tables
32 figures
244 pages and in-depth TOC on "Veterinary Surgical Instruments Market "
http://www.marketsandmarkets.com/Market-Reports/veterinary-surgical-instrument-market-212886010.html
Early buyers will receive 10% customization on this report.

The veterinary surgical instruments market witnessed healthy growth during the last decade and is expected to grow at a CAGR of 6.6% between 2016 and 2021 to reach 1029.0 Million by 2021.

The growth in this market is majorly attributed to factors such as rising animal healthcare expenditure, rising pet adoption, increasing number of veterinary practitioners and their growing income levels in developed regions, and increasing demand for pet insurance.


The global veterinary surgical instruments market is segmented based on product, animal, application, and geography. Based on product type, the market is segmented into sutures, staplers and accessories, handheld devices, electro-surgery instruments, and others. The handheld devices are further segmented into forceps, scalpels, surgical scissors, hooks & retractors, and trocars & cannulas. Based on animal type, the market is segmented into small animals and large animals.

The small animals segment is further segmented into canines, felines, and other small animals, while the large animals segment is further segmented into equines and other large animals. Based on the application the veterinary surgical instruments market is segmented into soft- tissue surgery, sterilization surgery, gynecology & urology, dental surgery, orthopedic surgery, ophthalmic surgery and others. Similarly, on the basis of geography, the veterinary surgical instruments market is segmented into EuropeNorth-AmericaAsia-Pacific, and Rest of the World.

In 2015, sutures, staplers, and accessories accounted for the largest share of the global veterinary surgical instruments. However, electro-surgery instruments segment is expected to witness the highest growth over the next five years. The high growth in this segment can be attributed to the advantages such as easy handling, high sensitivity, accuracy, and rapid healing offered by the electrode pencils used in various surgeries of small and large animals.

Speak to our research experts:
http://www.marketsandmarkets.com/speaktoanalyst.asp?id=212886010

North America is the largest regional segment for veterinary surgical instruments owing to the well-established animal healthcare market. The largest share of this regional segment is driven by rising companion animal adoption and healthcare expenditure, growing number of veterinary practitioners and their income levels, and rising demand for pet insurance. However, the market in the Asia-Pacific region is expected to grow at the highest CAGR, owing to rising pet adoption and increasing demand for animal-derived food products in India and China.

The market players, namely, B. Braun Vet Care GmbH (Germany), Medtronic Plc. (Ireland), Ethicon Inc. (U.S.), and JORGEN KRUSSE A/S (Denmark) held the major share of the veterinary surgical instruments market and will continue to dominate the market between 2016 and 2021.

Some of the major players operating in this market are Jorgensen Laboratories (U.S.), Smiths Group Plc (U.K.), Neogen Corporation (U.S.), Integra LifeSciences Holdings Corporation (U.S.), Ethicon Inc. (U.S.), Steris Corporation (U.S.), DRE Veterinary (U.S.), GerMedUSA, Inc. (U.S.), Surgical Holdings (U.K.), Sklar Surgical Instruments (U.S.), World Precision Instruments, Inc. (U.S.), Surgical Direct (U.S.), Antibe Therapeutics Inc. (Canada), and iM3 (U.S.).

Monday, 3 December 2018

Cardiovascular Ultrasound System Market Worth 1.66 Billion USD by 2021

Cardiovascular Ultrasound System Market Test Type (Transesophageal, Stress, Transthoracic, Fetal), Technology (2D, 3D & 4D, Doppler Imaging), Device Display (Black & White, Color), End User (Hospitals, Home Care, Ambulatory) - Forecast to 2021" published by MarketsandMarkets, the market is projected to reach USD 1.66 Billion by 2021 from USD 1.27 Billion in 2016, growing at a CAGR of 5.4% during the forecast period (2016-2021).
Browse 93 market data Tables and 40 Figures spread through 164 Pages and in-depth TOC on"Cardiovascular Ultrasound System Market "
Early buyers will receive 10% customization on this report. 
The report provides a detailed overview of the major drivers, restraints, challenges, opportunities, current market trends, and strategies impacting the cardiovascular ultrasound market along with the estimates and forecasts of the revenue. Increasing incidence of cardiovascular diseases, technological advancements, and advantages of echocardiography over invasive cardiac diagnostic procedures are the major drivers for the Cardiovascular Ultrasound System Market. However, insufficient reimbursement scenario and economic impact of adopting new technologies are restraining the growth of the market.
The Cardiovascular Ultrasound System Market is broadly segmented into test type, technology, device display, end user, and region. Based on test type, the market is categorized into transthoracic echocardiogram, stress echocardiogram, transesophageal echocardiogram, and fetal & intracardiac echocardiogram. The stress echocardiogram segment is expected to account for the largest share of the market in 2016. This is due to the major advantage of the stress echocardiogram that it can provide data of the cardiac muscles and valves before and after the stress of the heart muscle.
On the basis of technology, the Cardiovascular Ultrasound System Market is segmented into 2D, 3D & 4D, and Doppler imaging. The 2D technology is estimated to account for the largest share of the market in 2016, whereas the 3D & 4D technology segment is estimated to grow at the highest CAGR during the forecast period.
On the basis of device display, the market is segmented into color display and black & white (B/W) display. The color display segment is expected to register the highest growth in 2016.
On the basis of end user, the Cardiovascular Ultrasound System Market is categorized into hospitals, cardiology centers, ambulatory, home care, and other end users (research institutes, medical device and pharmaceutical companies). The hospitals segment is expected to account for the largest share of the market in 2016. The home care & ambulatory segment is estimated to register the highest CAGR during the forecast period due to increase in the usage of echocardiographs at the patient's house itself.

Key players in the Cardiovascular Ultrasound System Market include GE Healthcare (U.S.), Philips healthcare (The Netherlands), Siemens Healthcare (Germany), Hitachi Medical Corporation (Japan), and Toshiba Medical Systems Corporation (Japan).

Patient Portal Market Size, Market Growth Projection to 2023

The growth of the overall patient portals market can be contributed to the federal mandates like meaning use, growing patient centric appro...