Monday, 17 September 2018

Future of Operating Room Management Market in Healthcare Industry

The global operating room management market is expected to account for USD 2.01 billion in 2017, and projected to reach USD 3.41 billion by 2022 from, at a CAGR of 11.2%.


Operating room management market is segmented by solution, delivery mode, component, end user, and region.
The solution segment is further segmented by data management & communication solutions, anesthesia information management systems, operating room supply management solutions, operating room scheduling solutions, performance management solutions, and other solutions. In 2017, the supply chain management solutions segment is expected to grow at the highest CAGR in the market during the forecast period.
On the basis of delivery mode, cloud-based solutions segment is expected to grow at the highest rate during the forecast period (2017-2022). These solutions are preferred by end users owing to the advantages it offers such as the ability to reuse existing servers and easy implementation of backup and disaster recovery systems.
On the basis of component, the software segment is expected to grow at the highest rate during the forecast period. The growth of this segment can primarily be attributed to the growing installation of ORM software, coupled with the high cost of software and other associated costs such as licensing.
Hospitals are the dominant end users of operating room management solutions and this segment is expected to grow at the highest rate during the forecast period. The growth of this segment is attributed to the increasing utilization of ORM solutions in hospitals to curtail costs and improve time management in ORMs.
Geographically, the operating room management market in the APAC region is expected to witness the highest CAGR during the forecast period. This growth is attributed to the increasing need to curb healthcare costs, investments & reforms to modernize the healthcare system, and improving IT infrastructure are driving the growth of operating room management market in the region.

                                      Operating Room Management Market
The operating room management market offers lucrative growth opportunities in emerging markets (such as India, China, Brazil, and Mexico) to market players. Booming medical tourism in these countries and technological advancements in hospitals are additional factors aiding the growth of these markets.

Wednesday, 12 September 2018

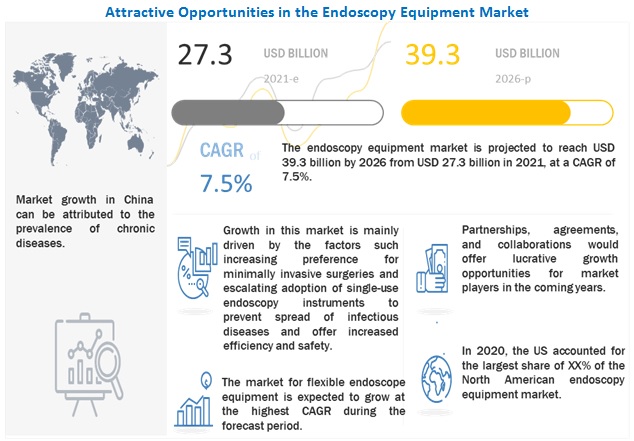
Rising Prevalence of Diseases That Require Endoscopy Providing Market Growth Opportunities

"Endoscopy Equipment Market by Product (Endoscope (Flexible, Rigid, Capsule) Visualization Systems, Endoscopic Ultrasound, Insufflator)), Application (GI Endoscopy, Laparoscopy, Cystoscopy, Bronchoscopy, Colonoscopy, Arthroscopy) - Global Forecast to 2022", published by MarketsandMarkets™


Key factors driving the growth of this market include favorable government initiatives, rising number of hospitals and growing hospital investments in endoscopy facilities, technological advancements, and rising prevalence of diseases that require endoscopy.


Download FREE Brochure @ https://www.marketsandmarkets.com/pdfdownload.asp?id=689


The global market is projected to reach USD 34.82 Billion by 2022 from an estimated USD 25.58 Billion in 2017, at a CAGR of 6.4% 


In 2017, North America is expected to account for the largest share of the Endoscopy Equipment Market, followed by Europe. Factors such as a favorable reimbursement scenario in the US, rising incidence of cancer, increasing investments by hospitals to purchase new endoscopic equipment, increasing research activities to improve endoscopy, and implementation of a new funding model for Canadian hospitals are contributing to the large share of North America.


The key players in the global Endoscopy Equipment Market are Olympus (Japan), KARL STORZ (Germany), Stryker (US), Boston Scientific (US), Ethicon (US), Fujifilm (Japan), Medtronic (Ireland), Hoya (Japan), CONMED (US), Richard Wolf GmbH (Germany), Smith & Nephew (UK), Cook Medical (US), Cogentix Medical (US), and B. Braun (Germany).


To Know More @ https://www.marketsandmarkets.com/Market-Reports/endoscopy-devices-market-689.html

FDA and Ce Mark Approvals Driving the Adoption of Surgical Sealants and Adhesives

Growth in this market is majorly attributed to factors such as increasing need to manage blood loss in patients, growing rate of surgeries being performed annually, greater uptake of technologically advanced products, and increasing FDA and CE Mark approvals. Moreover, factors like rising geriatric population, increasing prevalence and incidence of chronic disorders, and increasing trauma and accident cases are driving the adoption of these sealants and adhesives.


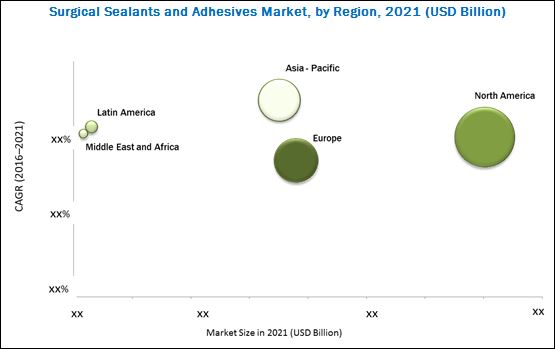
"Surgical Sealants and Adhesives Market witnessed a healthy growth rate during the last decade and is expected to grow at a CAGR of 9.6% between 2016 and 2021 to reach 2.96 Billion by 2021."

The Surgical Sealants and Adhesives Market is segmented on the basis of product, indication, application, and region. 

In 2016, North America is expected to account for the largest share of the market. The largest share of this regional segment is driven by rising healthcare expenditure, the presence of many large and well-equipped hospitals, greater uptake of technologically advanced medical products, increasing FDA approvals for surgical sealants, and the presence of major market players in this region. 
However, the market in the Asia-Pacific region is expected to grow at the highest CAGR, owing to growing per capita income, increasing medical tourism, the presence of less stringent regulations, and growing demand for quality healthcare. In addition, increasing investments by major players in this region is propelling the market further.


Target Audience:
  • Medical Device Companies
  • Pharmaceutical and Biotechnology Companies
  • Life Sciences Companies
  • Hospitals and Clinics
  • Academic Research Institutes
  • Government Institutes
  • Market Research and Consulting Firms
  • Venture Capitalists and Investors
Baxter International, Inc. (U.S.), Johnson & Johnson (Ethicon, Inc.; U.S.), CryoLife, Inc. (U.S.), and C.R. Bard, Inc. (U.S.) held the major share of the Surgical Sealants and Adhesives Market and will continue to dominate the market between 2016 and 2021.
Some of the major players operating in this market are Medtronic plc (U.S.), Sanofi Group (France), B. Braun Melsungen AG (Germany), Cohera Medical, Inc. (U.S.), Ocular Therapuetix, Inc. (U.S.), Vivostat A/S (Denmark), and Sealantis Ltd. (Israel).

Tuesday, 11 September 2018

Increasing Use of Synthesized Oligonucleotides in Molecular Diagnostics and Clinical Applications

The growth of oligonucleotide synthesis market is mainly driven by the increasing research activities in the pharma and biotech sectors and the rising demand for innovative diagnostic and therapeutic techniques.


This report segments the market into product, application, end user, and region. 

Based on product, the market is segmented into synthesized oligonucleotides, reagents, and equipment. In 2017, synthesized oligonucleotides are estimated to account for the largest share of the total market, followed by reagents. The growth of the synthesized oligonucleotides segment is attributed to the increasing number of applications of synthesized oligonucleotides in research, diagnostics, and therapeutics.


Based on product, the synthesized oligonucleotides market is segmented into primers, probes, large-scale synthesis oligonucleotides, intermediate-scale synthesis oligonucleotides, and linkers & adaptors. Primers are expected to account for the largest share of the synthesized oligonucleotides market in 2017. The intermediate-scale synthesis oligonucleotides segment is projected to register the highest CAGR, due to the rising demand for synthesized oligonucleotides and innovations in manufacturing techniques to produce intermediate-scale oligonucleotides.

Based on end user, the oligonucleotide synthesis market is segmented into academic research institutes, pharmaceutical and biotechnology companies, diagnostic laboratories, and other end users. The diagnostic laboratories segment is expected grow at the highest CAGR during the forecast period. This growth is attributed to the rising diagnostic applications of oligonucleotides and the growing field of molecular diagnostics.


Monday, 10 September 2018

Globalization of Clinical Trial Activities Increasing Market Growth Opportunities

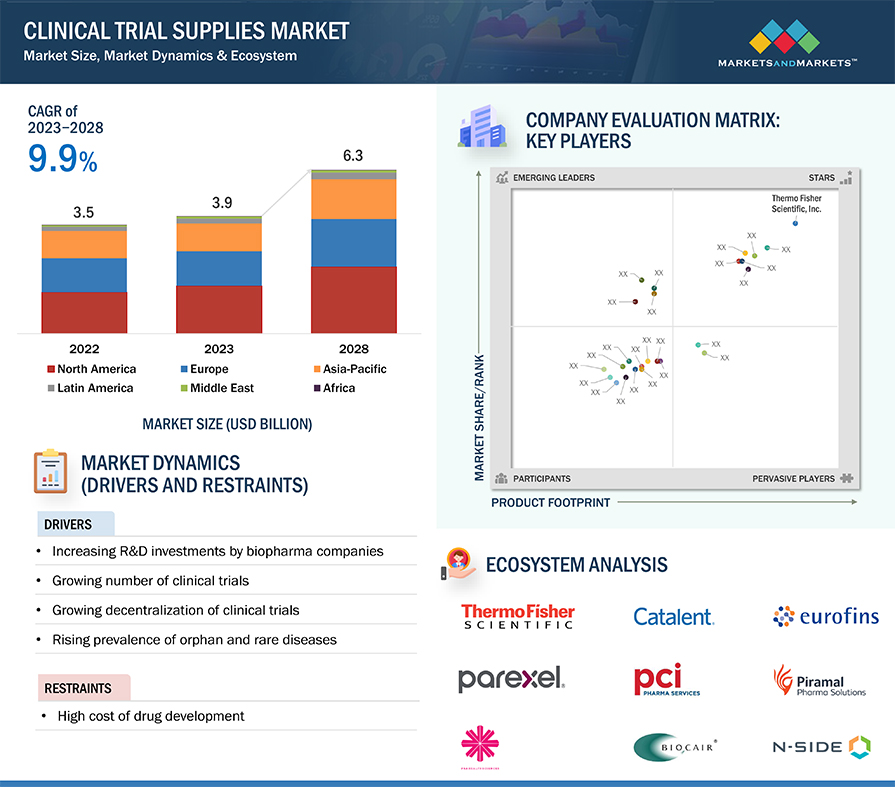
Clinical Trial Supplies Market by products & Services (Logistics & Distribution, Manufacturing, Packaging and Labeling), Phases (Phase I, Phase II, Phase III) & Therapeutic Areas (CNS & Mental Disorders, Cardiovascular, Oncology) - Global Forecast to 2020", published by MarketsandMarkets


Clinical trial supplies market based on products and services, phases, therapeutic areas, and regions. 
Among the various products and services, the logistics and distribution services segment is expected to account for the largest share of the market and is projected to grow at the highest CAGR from 2015 to 2020. The high growth in this segment can be attributed to the factors such as globalization of clinical trials and increasing outsourcing of services.
On the basis of phases, the clinical trial supplies market is segmented into phase I, phase II, and phase III. The phase III segment is expected to account for the largest share of the global clinical trial supplies market in 2015. Large sample size of patients and high cost of phase III trials are the factors propelling the growth of this market.\
Therapeutic areas, included in the clinical trial supplies market are oncology, cardiovascular diseases, respiratory diseases, CNS and mental disorders, dermatology disorders, blood disorders, infectious diseases, and others. The oncology segment is expected to account for the largest share of the global clinical trial supplies market in 2015. Increase in cancer incidences and government funding for cancer research are factors driving the growth of this market.
Based on regions, the global clinical trial supplies market is segmented into North America, Europe, Asia-Pacific, and the Rest of the World (RoW). North America is expected to account for the largest share of the market during the forecast period. Growth in this regional segment is driven by factors such as rising prevalence of chronic diseases, growing number of clinical trials, and the increasing number of life sciences research activities in North America.

Key players in the Clinical Trial Supplies Market include Alamc Group LTD (U.K.), Biocair (U.K.), Catalent Pharma Solutions, Inc. (U.S.), KLIFO A/S (Denmark), Movianto (Germany), PCI Services (U.S.), Patheon, Inc. (U.S.), PAREXEL International Corporation (U.S.), Sharp Packaging Services (U.S.), and Thermo Fisher Scientific, Inc. (U.S.)

Friday, 7 September 2018

Growth in Aging Population and the Associated Increase in the Prevalence of Parkinson’s Disease


Parkinson’s disease therapeutic drugs act upon the central nervous system to control or reduce the symptoms of Parkinson’s disease. 


Globally, the Parkinson’s disease treatment market is witnessing a moderate growth due to factors such as increasing prevalence of Parkinson’s disease; rising geriatric population; and support for research on Parkinson’s disease. 

Over the last few decades, key players operating in this market are focusing on offering new and innovative products. Based on drug class, the Parkinson’s disease therapeutic drugs market is segmented into carbidopa/levodopa dopamine receptor agonists, MAO-inhibitors, COMT-inhibitors, anticholinergics and other drugs. The carbidopa/levodopa segment is expected to register the highest CAGR during the forecast period. This is due to carbidopa/levodopa drugs are more potent and widely used in the treatment of Parkinson’s disease in comparison to other therapeutic drugs.


By distribution channel, the market is segmented into hospital pharmacies, retailer pharmacies, and online pharmacies. The online pharmacies segment is expected to register the highest growth rate during the forecast period. Advancements such as 24/7 availability, home delivery, and discount on medicines are driving factors for online pharmacies segment.

On the basis of patient care setting, the market is categorized into hospitals and clinics. The hospitals segment is estimated to grow at the fastest rate during the forecast period. The growth of this segment can be attributed to the availability of diagnostics laboratories in the hospital and the presence skilled neurologists.

The Parkinson’s disease treatment market is classified based on regions into North America, Europe, Asia, and the Rest of the World (RoW). Asia is expected to grow at the highest CAGR during the forecast period. Presence key market players and rising aging population are the major factors driving the Parkinson’s disease treatment market in this region.


Growth of Quality Management System in Healthcare Industry


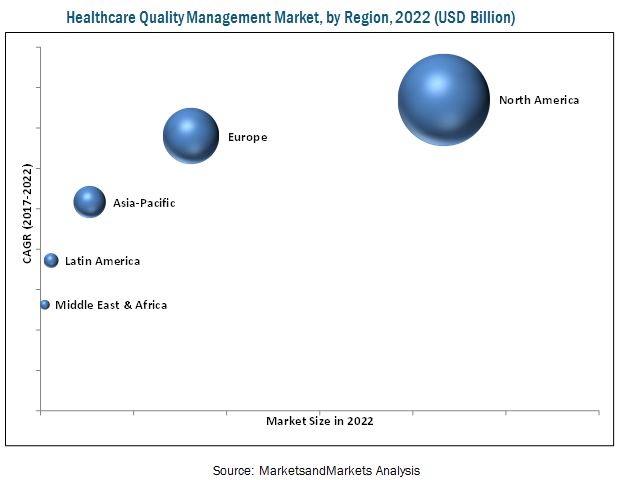
Government mandates for healthcare providers to report quality & improve the performance of care provided, increase in the volume of unstructured data in the healthcare industry, and need to curtail healthcare costs & medical errors are the major factors driving the growth of the market. However, data security concerns and the high cost of quality reporting are expected to restrain the growth of this market to a certain extent.

"The global Healthcare Quality Management Market is projected to reach USD 3.31 Billion by 2022 from USD 1.51 Billion in 2016, at a CAGR of 14.2%"

The global market is segmented on the basis of type, delivery mode, application, end user, and region.


This report also provides market information on major regional segments, namely, North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.


On the basis of type, the market is segmented into business intelligence & analytics solutions, physician quality reporting solutions, clinical risk management solutions, and provider performance improvement solutions. In 2016, the business intelligence & analytics solutions dominated the market. The large share of this segment can primarily be attributed to the need of healthcare providers to reduce the soaring operating costs, rising demand for quality healthcare, government measures to promote value-based care, and the increasing number of claims denied from insurers.

Based on delivery mode, the web-& cloud-based solutions dominated the market. The large share of this segment is mainly attributed to the flexibility of working from remote areas, affordability, and automated updating features of web-& cloud-based solutions.

By application, the market is classified into data management and risk management. The data management segment is expected to register the highest CAGR during the forecast period. The large share of this segment is attributed to the increasing volume of disparate data and the requirement of quality-based reports by regulatory bodies.

The major end users of healthcare quality management market are hospitals, ambulatory care centers, payers, and ACOs. The hospitals segment accounted for the largest share of the global market in 2016. Growing HCIT adoption, increasing focus on patient safety, significant growth in healthcare spending, rising medical error rates, increasing healthcare costs, and government mandates to follow quality measures are the major factors supporting the adoption of healthcare quality management solutions in hospitals.


Patient Portal Market Size, Market Growth Projection to 2023

The growth of the overall patient portals market can be contributed to the federal mandates like meaning use, growing patient centric appro...